INVESTMENT MANAGEMENT | ALPHARETTA, GEORGIA
Your portfolio should have a purpose beyond performance.
Investment performance matters.
But the right portfolio is not simply the one that performed best last year. It is the one designed around what your money needs to accomplish.
Growth. Retirement income. Capital preservation. Future purchases. Charitable giving. Family support. A business transition. A legacy for the next generation.
Fountain Wealth Partners builds and manages diversified investment portfolios around your goals, risk tolerance, time horizon, income needs, tax circumstances, and broader financial plan.
Your investment strategy should serve your life—not the other way around.
Why software alone falls short: How automated algorithms fail during critical life transitions, tax adjustments, and market volatility.
The four pillars of human wealth management: How direct access to a dedicated senior advisor, 100% fee-only fiduciary independence, comprehensive wealth coordination, and long-term continuity protect your legacy.
What you can expect as a client: The exact written deliverables, fee transparency, and local face-to-face access you gain by partnering with an independent CFP® lead advisor.
Why software alone falls short: How automated algorithms fail during critical life transitions, tax adjustments, and market volatility.
The four pillars of human wealth management: How direct access to a dedicated senior advisor, 100% fee-only fiduciary independence, comprehensive wealth coordination, and long-term continuity protect your legacy.
What you can expect as a client: The exact written deliverables, fee transparency, and local face-to-face access you gain by partnering with an independent CFP® lead advisor.
Direct Partner Access with David Fountain, CFP® professional • 100% Fee-Only Fiduciary • 12600 Deerfield Pkwy, Suite 100, Alpharetta, GA • (770) 650-9392
Advisory services offered through Financial Consultants Group, Inc. d/b/a Fountain Wealth Partners, an SEC Registered Investment Advisor. SEC registration does not imply a certain level of skill or training. Past performance does not guarantee future results. Investing involves risk and possible loss of principal.
Before deciding what you should own, we want to understand what your wealth needs to do.
Two families with identical investment balances may appropriately have very different portfolios.
One may be five years from retirement and still accumulating wealth.
Another may already depend upon the portfolio to provide substantial monthly income.
One may want to maximize the wealth eventually transferred to children.
Another may be preparing for a major purchase, business sale, charitable gift, or other liquidity need.
That is why our investment process begins with the financial plan.
We seek to understand:
- What is this money intended to accomplish?
- When will you need it?
- How much income should the portfolio provide?
- How much risk can you financially afford to take?
- How much volatility are you personally comfortable accepting?
- What other assets and sources of income do you have?
- What tax considerations should influence the strategy?
- What circumstances might require the portfolio to change?
Only then should the investment decisions begin.
Diversified by design. Flexible where it matters.
We do not believe every investment decision can be reduced to choosing between “active” or “passive” management.
Both can have an appropriate role.
Our investment philosophy combines disciplined research, broad diversification, thoughtful active and passive management, and an ongoing focus on risk, costs, taxes, and the role each investment is intended to serve. We believe sophisticated advice should still feel personal. Explore how we structure allocations across market cycles in our
Strategy & Allocation
practice.
Depending upon the needs of the client and portfolio, investment strategies may incorporate:
- Broad-market and factor-based exchange-traded funds
- Actively managed investment strategies
- Individual equities
- Municipal and taxable fixed income
- International investments
- Thoughtful placement of investments among taxable and retirement accounts (asset location)
- Diversifying strategies
- Cash and short-term reserves
- Broad-market and factor-based exchange-traded funds
- Actively managed investment strategies
- Individual equities
- Municipal and taxable fixed income
- Short- and intermediate-term bonds
- International investments
- Inflation-sensitive investments
- Diversifying strategies
- Cash and short-term reserves
We evaluate each allocation within the context of the complete portfolio rather than simply selecting investments individually.
The objective is to create a portfolio in which the pieces have defined roles and work together toward the family's broader financial goals.
The least expensive investment is not always the most appropriate—and the most complicated is not necessarily the best.
Passive investments can provide efficient, low-cost exposure to broad areas of the market.
Active management may offer advantages where security selection, credit analysis, risk management, or changing market conditions can create meaningful differences among investments.
Rather than adopting one philosophy for every asset class, we evaluate where active management may add value and where a passive approach may provide a more efficient solution.
That may lead to greater use of passive strategies in highly efficient areas of the equity markets while using experienced active managers more selectively in areas such as fixed income, credit, smaller companies, international markets, or other specialized strategies.
Our focus is not on being active or passive. It is using the approach we believe is most appropriate for the job.
The amount of risk you can take and the amount you need to take are not always the same.
Successful investors sometimes accumulate portfolios over decades.
Different accounts. Former employer plans. Individual stocks. Funds purchased at different times. Investments inherited from family. Positions that have appreciated significantly.
Individually, each holding may seem reasonable.
Collectively, the portfolio may contain more concentration, duplication, tax exposure, or risk than the investor realizes.
We evaluate risk across the complete portfolio.
That includes considering:
- Equity and fixed-income exposure
- Concentration in individual companies, RSUs, or sectors
- Interest-rate and credit risk
- Geographic exposure
- Liquidity and cash reserves
- Tax consequences and embedded gains
- Correlations among investments
- Income requirements
- Time horizon
- The potential impact of significant market declines
The goal is not to eliminate risk. Investing necessarily involves uncertainty.
The goal is to understand which risks you are taking, why you are taking them, and whether they remain appropriate for what your wealth needs to accomplish.
In many families, one spouse naturally oversees day-to-day investments. Long-term security requires that both spouses understand the complete balance sheet and know their advisory team.
If one spouse passes away or becomes ill, the surviving spouse should never be left trying to navigate complex accounts and legal structures alone. The planning established today provides clarity and continuity when your family needs it most.
Retirement changes the job of the portfolio.
During your working years, market declines may be uncomfortable, but employment income can allow you to continue investing and give the portfolio time to recover.
Retirement can change that equation.
The portfolio may now need to provide dependable distributions while also supporting decades of future spending and maintaining enough growth to help offset inflation.
That makes the relationship between investment strategy, cash reserves, income needs, taxes, and withdrawal planning increasingly important. Learn more about how we coordinate distributions and longevity in our
Retirement Planning practice.
We help determine how much should remain positioned for long-term growth, what assets may provide income and stability, where near-term spending needs should come from, and how the portfolio should evolve as circumstances change.
Retirement investing should not simply be about becoming more conservative.
It should be about aligning risk with the job your wealth now needs to perform.
Investment returns are only part of what ultimately matters.
For taxable investors, two portfolios with similar investment returns can produce very different after-tax results.
That is why we incorporate tax considerations into our investment process where appropriate. Explore our broader approach to
Tax-Aware Wealth Planning
Depending upon your circumstances, that may involve:
- Thoughtful placement of investments among taxable and retirement accounts (asset location)
- Municipal versus taxable fixed-income analysis
- Capital gain and loss management
- Tax-loss harvesting opportunities
- Managing appreciated or concentrated positions
- Coordinating portfolio withdrawals
- Charitable gifting of appreciated securities
- Evaluating the tax impact before significant portfolio changes
- Coordinating investment decisions with broader tax-planning opportunities
Taxes should not dictate every investment decision.
But you shouldn't ignore them either.
Fountain Wealth Partners provides tax-aware wealth planning and portfolio coordination. We
do not provide formal tax preparation, CPA, or legal services. All strategies are executed in collaboration with your qualified tax advisor.
Our goal is to consider investment and tax consequences together while coordinating with your CPA or other qualified tax professional when appropriate.
Starting a new advisory relationship does not mean everything you own needs to be sold.
Many clients come to Fountain Wealth Partners with portfolios accumulated over years or even decades.
Some holdings may remain entirely appropriate.
Others may create unnecessary risk, duplication, expenses, or tax consequences.
Some investments may carry substantial unrealized gains that deserve careful consideration before making changes.
We begin by understanding what you currently own and why.
We then evaluate how your existing portfolio compares with the strategy we believe fits your financial plan.
When changes are warranted, we can develop a thoughtful transition strategy that considers investment priorities, taxes, transaction costs, liquidity needs, and timing.
The goal is to understand which risks you are taking, why you are taking them, and whether they remain appropriate for what your wealth needs to accomplish.
Customized investment management for North Georgia's leading families, executives, and business owners
We design purpose-built investment portfolios tailored to the distinct financial complexities of our clients across North Fulton and North Georgia.
- Dedicated cash-flow distribution reserves
- Structured asset location across taxable and Roth accounts
- Systematic rebalancing to manage sequence-of-returns risk
- Staged multi-year diversification schedules
- Structured 10b5-1 executive trading plans
- Tax-bracket management and AMT coordination with your CPA
- Cash Balance Plan & defined benefit portfolio design
- Post-sale liquidity diversification and tax-aware reinvestment
- Personal cash-flow synchronization separate from business assets
Portfolios should evolve when circumstances change;
Not when markets become uncomfortable.
Investment management is an ongoing process.
We continually evaluate portfolios in light of market conditions, valuations, economic developments, interest rates, investment opportunities, risk characteristics, tax considerations, and changes within the underlying investments we use.
We also consider something even more important:
Changes in your life.
Retirement. A business sale. An inheritance. A major purchase. The death of a spouse. A change in income. A charitable gift. A new estate strategy.
Those events may matter more to your portfolio than the latest market headline. We are dedicated to being a team that knows the family—not just the account numbers.
When circumstances warrant a change, we make adjustments thoughtfully and with the broader financial plan in mind.
Once we understand the financial picture, an advisor can explain how Fountain Wealth Partners would work with you and the advisory fee that would apply to the relationship.
Independent custody provides an important separation of responsibilities.
Fountain Wealth Partners provides investment advice and portfolio management, but we do not take custody of client assets.
Client accounts remain titled in the client's name and are held with independent qualified custodians, including Charles Schwab & Co. and Axos.
The custodian maintains the accounts, executes transactions, provides statements and tax documents, and safeguards client assets.
Fountain Wealth Partners receives authorization to manage investments within the scope of our advisory agreement.
This separation allows us to focus on providing advice and managing the portfolio while client assets remain with an independent financial institution.
A well-managed portfolio is important.
A well-coordinated financial life is better.
Investment management is one component of the work we do.
For
Wealth Managementtclients, investment decisions are considered alongside retirement planning, cash flow, taxes, estate and legacy priorities, charitable giving, business interests, and family objectives. We recognize that some of the most valuable financial decisions happen before they become urgent.
That broader perspective can help answer questions that investment performance alone cannot:
- Should you take more risk—or do you already have enough?
- Should excess cash be invested—or used for another priority?
- Should appreciated investments be sold, held, or given to charity?
- Should portfolio withdrawals come from taxable assets or retirement accounts?
- Should an investment strategy change as retirement approaches?
Beginning Your Advisory Relationship
We manage the onboarding and transition process thoughtfully to avoid unnecessary taxable events and establish seamless continuity. To learn more about our structured engagement model, explore Our Process
1. Clarify Your Goals During a 20-Minute Discovery Conversation
We begin with a focused, confidential conversation to review your current portfolio, understand your family's long-term objectives, and determine mutual fit.
2. Review Your Written Portfolio & Tax Roadmap
We deliver an objective investment strategy detailing your target asset allocation, risk parameters, and an actionable tax-location schedule.
3. Implement & Transition Assets In-Kind
We coordinate the paperwork to transition your securities in-kind from your previous custodian, and rebalance systematically over time to manage tax impact.
Common Questions About Investment Management
How are my investment assets protected and where are they held?
Your assets stay in your name at independent, SIPC-insured institutional custodians—never with Fountain Wealth Partners directly. Client accounts are held at Charles Schwab & Co. and Axos, providing you with continuous 24/7 online access, direct monthly statements, and complete institutional security.
How is your advisory fee structured?
We operate on a 100% fee-only fiduciary model. Wealth management fees are generally based on a transparent, tiered percentage of assets under management (AUM) with householding provisions. We earn no commissions, sales loads, or third-party referral fees. We fully explain the applicable arrangement before an engagement begins. For more details, visit our Fees & Fee-Only Approach page or review our Form ADV Part 2A on our Disclosures page.
How do you manage concentrated stock and executive equity?
For corporate executives and business founders in Alpharetta and North Fulton, we analyze the cost basis and holding periods of every position. We design structured diversification schedules and coordinate with your CPA to help manage capital gains impact over time.
How do you coordinate investment decisions with my CPA?
We coordinate directly with your CPA or qualified tax professional throughout the year. At tax time, we ensure 1099s and realized gain/loss summaries are readily available. Throughout the year, we collaborate on capital gains management, Roth conversion timing, and charitable gifting strategies to align your investments with your tax plan.
Can I transfer my existing portfolio without selling everything?
Yes. We transfer securities in-kind via standard institutional transfer processes without requiring automatic liquidation. Once transferred, we evaluate which holdings remain appropriate for your strategy and develop a phased, tax-conscious transition plan to align with your target allocation.
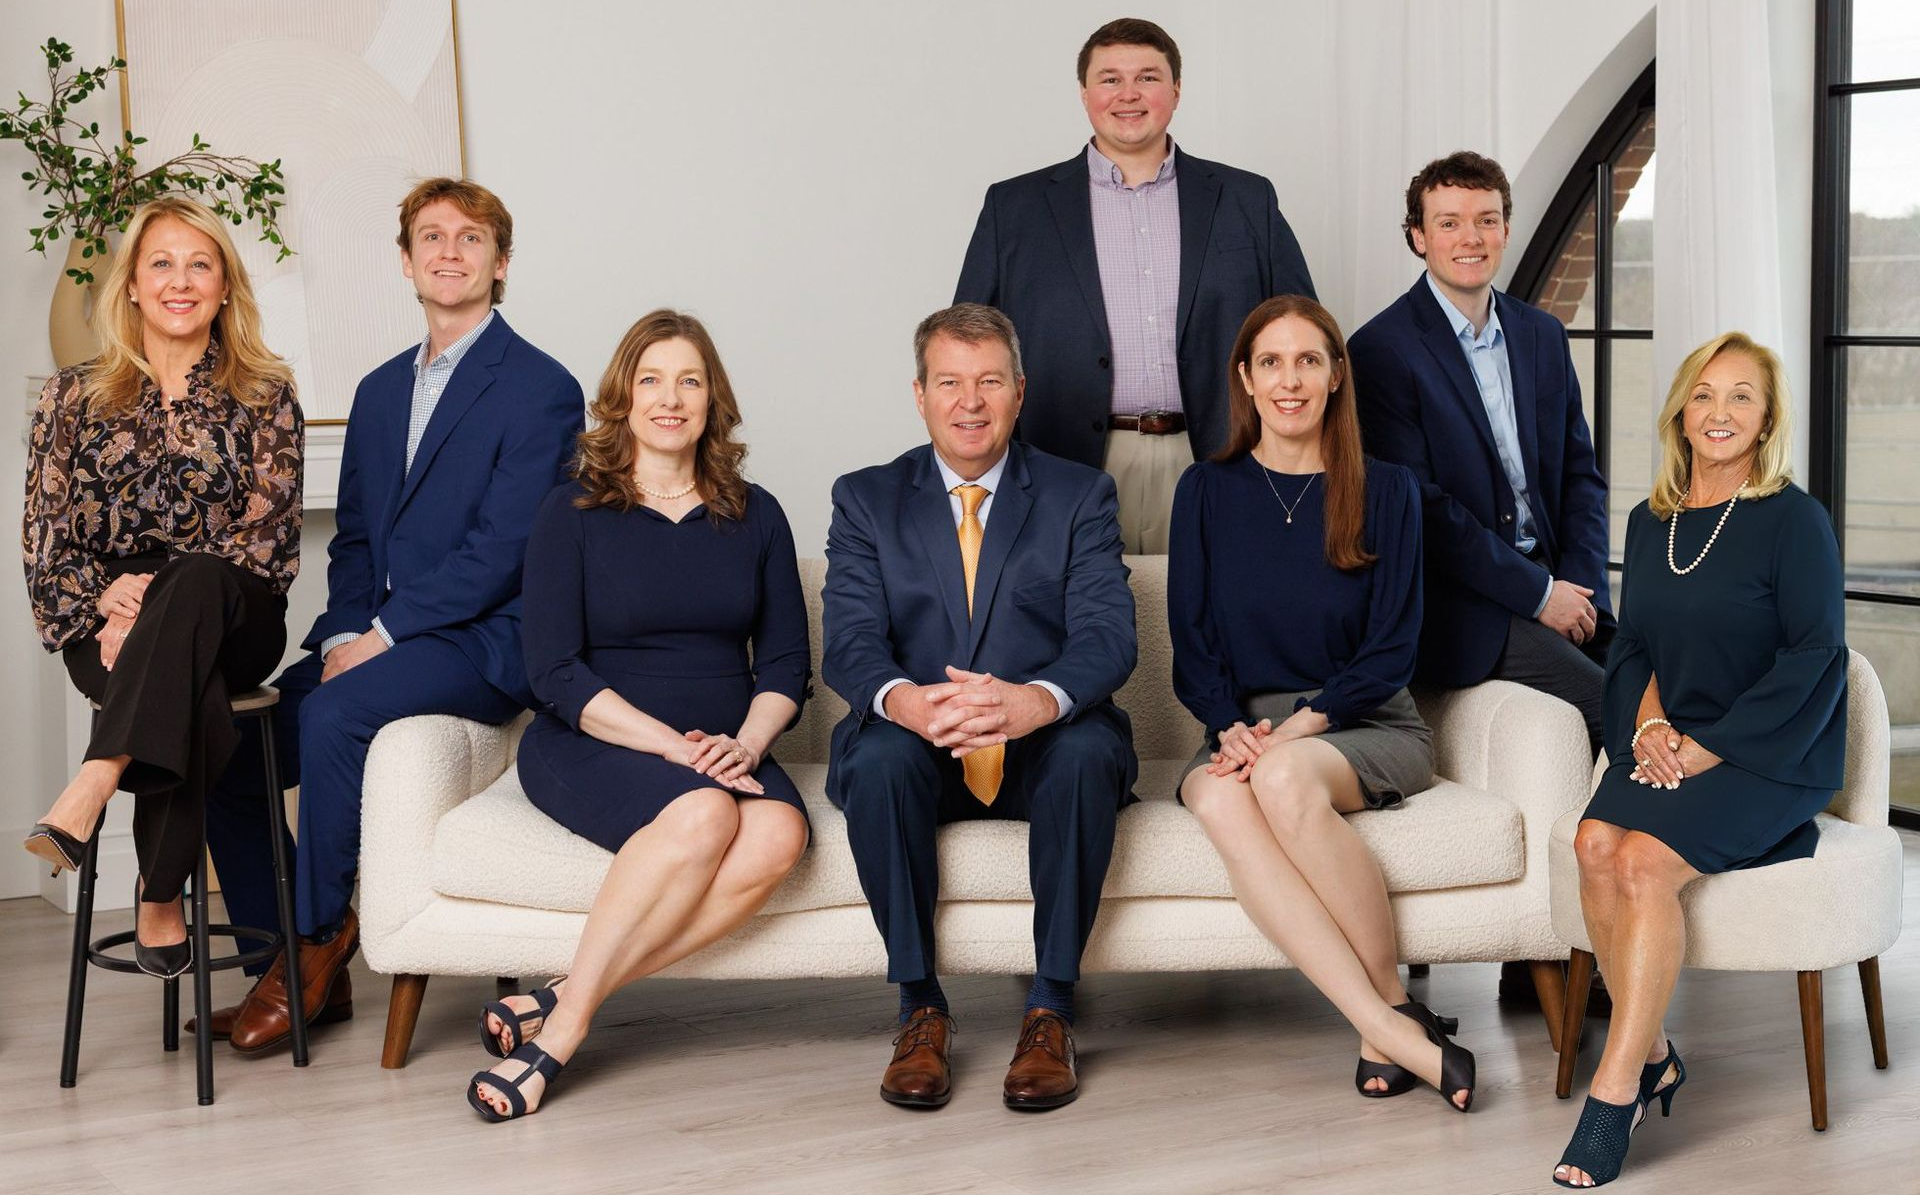
David Fountain, CFP® — Founder & Lead Advisor
A CONVERSATION
Is your portfolio still appropriate for the life you are planning?
You may already have a successful investment portfolio.
The question is whether it remains aligned with where you are today—and where you are going next.
An introductory conversation gives us an opportunity to understand your current investments, financial circumstances, the decisions ahead, and what you want your wealth to accomplish.
You don't need to make an investment change just to have the conversation.
A confidential, no-obligation opportunity to determine whether Fountain Wealth Partners may be the right fit for you and your family.
YOUR GOALS. OUR GUIDANCE. YOUR LEGACY.
Alpharetta (12600 Deerfield Pkwy, Suite 100) | Cumming | Serving clients throughout North Georgia and beyond
Regulatory Disclosures
Advisory services offered through Financial Consultants Group, Inc. d/b/a Fountain Wealth Partners, an SEC Registered Investment Advisor. SEC registration does not imply a certain level of skill or training. Advisory services are only offered to clients or prospective clients where Fountain Wealth Partners and its representatives are properly licensed or exempt from licensure. Past performance is no guarantee of future returns. Investing involves risk and possible loss of principal capital. No advice may be rendered by Fountain Wealth Partners unless a client service agreement is in place. View our
Disclosures (Form ADV Part 2A & Form CRS), Privacy Policy, and Terms of Service. Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.